Medical Practice Loans:
Independent medical practices live with a built-in timing problem.
You deliver care now. You wait to get paid later.
Meanwhile, payroll, malpractice premiums, rent, supplies, software costs, recruiting expenses, and day-to-day overhead keep moving on schedule. That gap is one of the biggest reasons practice owners start thinking more seriously about liquidity long before they feel an emergency.
A well-structured medical practice line of credit can help close that gap without forcing the practice into reactive decisions. Instead of scrambling when reimbursements lag or an opportunity appears, you have planned access to working capital that supports stability, growth, and independence.
For primary care groups, specialty clinics, and multi-provider practices, that matters more than ever.
Why medical practices need a cash buffer
A medical practice can be busy, profitable, and still feel cash pressure.
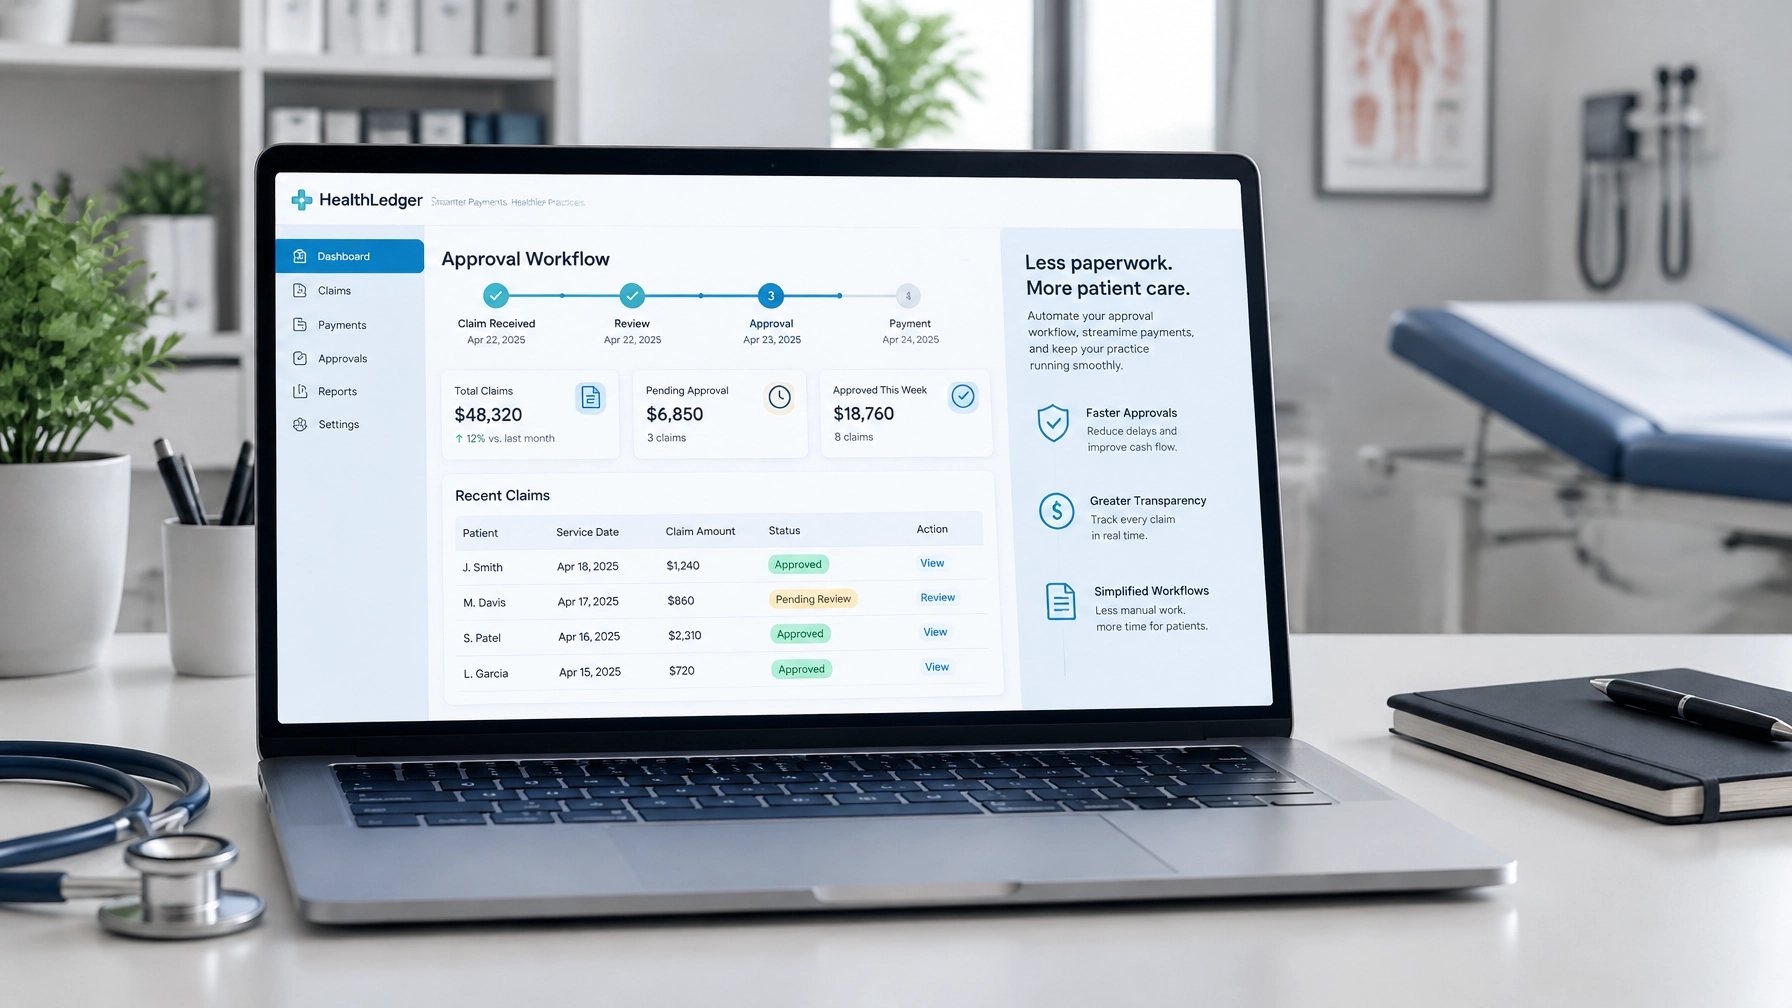
That is because healthcare revenue often arrives on a delay. Claims processing, payer reviews, denials, resubmissions, and reimbursement cycles can stretch collections far beyond when the care was delivered. The practice may be producing every day, but cash does not always arrive in step with production.
According to Fora Financial’s “Medical Practice Financing Trends” published July 13, 2026, 55% of medical practice owners say cash flow is their top operational challenge, driven by structural 60-to-120-day insurance reimbursement delays. The same report notes that many practices turn to short-term, revenue-based working capital advances to bridge gaps. That trend says a lot about the pressure practices are under, but it does not mean those products are the best solution. In many cases, they are simply the quickest reaction to a timing problem.
Source: https://www.forafinancial.com/blog/working-capital/medical-practice-financing/
A stronger approach is to build a cash buffer before pressure builds.
That is where a healthcare business loan structure like a revolving line of credit stands out. It gives the practice a controlled source of liquidity that can be used when needed, then reused as the balance is paid down. That is very different from relying on expensive emergency fixes every time reimbursements run behind.
Delayed cash is normal in healthcare, but panic should not be
Medical practice owners are used to complexity.
You manage provider schedules, coding accuracy, staffing, patient satisfaction, payer relationships, compliance, and rising operating costs. The last thing you want is for temporary timing gaps to dictate strategic decisions.
Without a cash buffer, a practice may feel forced to:
• Delay hiring a needed provider or key staff member
• Postpone software or technology upgrades
• Push off marketing or expansion plans
• Stretch vendors longer than preferred
• Carry stress around every reimbursement slowdown
• Consider outside ownership pressure before the practice is ready
With a medical practice line of credit, the goal is not to borrow recklessly. The goal is to remove timing pressure from decisions that should be made deliberately.
Why independence is becoming more important
The pressure to sell is not as simple as it once looked.
According to Mondaq’s October 5, 2026 update on healthcare private equity, private equity investment in physician practice management companies has fallen by roughly 50% versus 2025. The article points to new state regulations in California and Oregon restricting the friendly-physician model, while buyers are also demanding larger seller rollover equity of 20% to 40% and longer earnouts.
The takeaway for many independent practice owners is clear: staying independent is still attractive, but it requires resources.
If the exit environment is less favorable and more restrictive, many physicians will choose to keep building their own practice rather than sell under pressure. But independence is easier to maintain when the business has liquidity. A practice with access to working capital can make smart decisions on its own timeline instead of reacting to cash strain.
That is one reason interest in medical practice loans remains strong among operators who want to stay in control.
Where practices are using capital today
Capital demand in healthcare is not just about covering gaps. It is also about moving forward.
According to Averan Advisors’ “The Practice Operator Brief: Q4 2026,” published September 26, 2026, medical practices continue seeking capital for three major priorities:
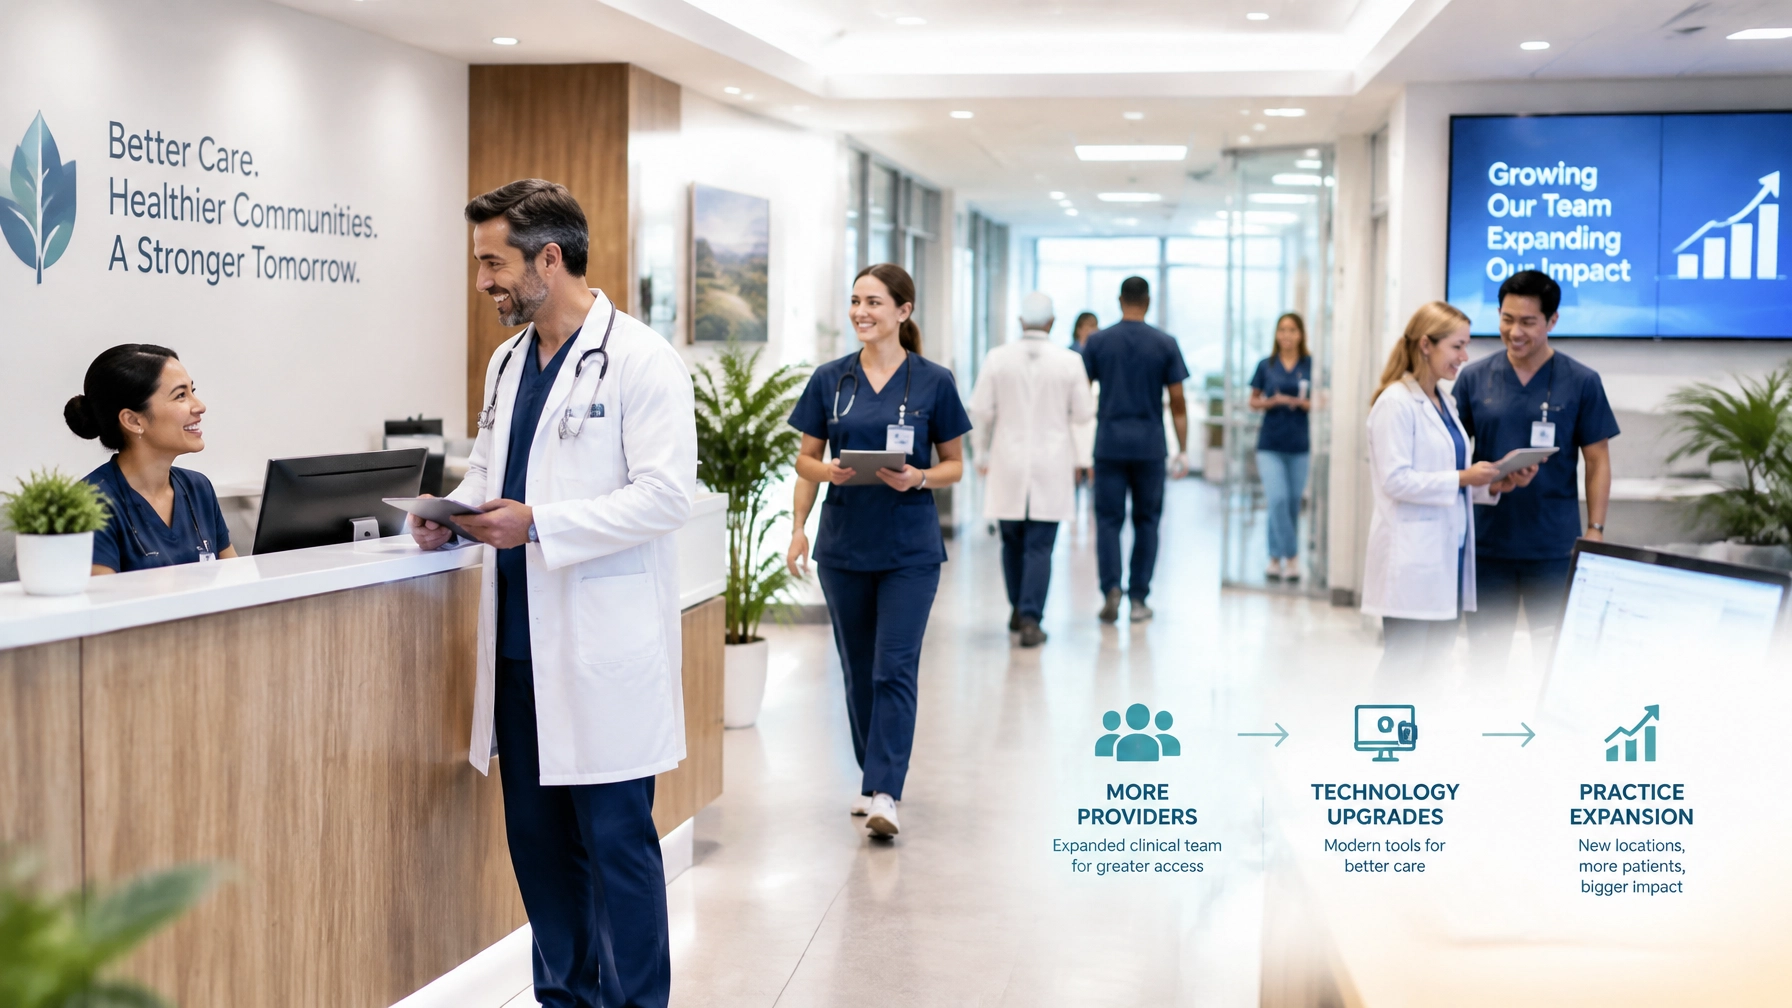
• Technology upgrades, including EHR and EMR systems and imaging
• Provider hiring and retention
• Expansion initiatives
Source: https://averanadvisors.com/resources/medical-practice/operator-brief/2026-q4/
Those uses are practical and familiar to independent operators.
A growing practice may need better systems before inefficiency starts affecting patient flow. A multi-provider group may need to hire ahead of demand to avoid bottlenecks. A specialty practice may want to expand into a larger space, add clinical capacity, or strengthen operations before launching a new location or service line.
These are not panic uses. These are strategic uses.
What a medical practice line of credit actually helps with
A true line of credit is not just for emergencies.
For many healthcare operators, it becomes a practical cash management tool that supports both stability and growth. Common uses include:
1. Smoothing reimbursement gaps
If insurance payments are lagging, the line can help cover normal operating costs without throwing the practice off course.
2. Protecting payroll and staffing
Strong staff retention matters in healthcare. A line of credit can help the practice stay consistent on payroll and hiring plans even when collections are temporarily uneven.
3. Supporting technology upgrades
Practice management software, EHR improvements, workflow tools, and clinical technology all support patient care and operational efficiency. Liquidity helps owners invest at the right time instead of waiting too long.
4. Preparing for expansion
Whether the practice is adding providers, expanding hours, opening another office, or refreshing a space, access to capital creates room to act with confidence.
5. Reducing pressure-driven decisions
When you know liquidity is available, you do not have to evaluate every short-term disruption as a crisis.
Why a line of credit is often more disciplined than reactive short-term funding
Some medical practices under pressure end up using short-term working capital advances because they need immediate relief from delayed receivables.
That is understandable, but it can create a cycle where the financing itself becomes another source of operational strain.
A medical practice line of credit is generally the more disciplined alternative because it is designed around flexibility and control:
• You draw only when needed
• You can keep capacity available for future needs
• It supports planning instead of repeated emergency borrowing
• It fits timing gaps without forcing a practice into one fixed use case
• It can be used for both operating stability and growth initiatives
For a practice owner thinking long term, that distinction matters.
Signs your practice may be ready for planned liquidity
Not every practice owner thinks about capital until there is a problem. But the best time to set up a line is often before the pressure arrives.
You may be ready to explore medical practice loans or a line of credit if:
• Insurance reimbursement timing is creating regular stress
• Payroll and overhead feel too dependent on perfect monthly collections
• You want to hire, but cash timing makes the decision harder
• You need to upgrade systems, software, or clinical workflow tools
• You are thinking about expansion within the next year
• You want more control and less dependence on outside pressure
• You prefer to build a buffer now instead of reacting later
How Jonicki Capital Consulting helps medical practices
Jonicki Capital Consulting helps business owners access practical working capital with a simpler, more personal process.
For medical practices, that means a few things that matter:
One advisor from start to finish
You work with one person throughout the process. You are not dropped into a giant lead marketplace and passed around.
Your information is not blasted to multiple lenders
That matters for professional operators who value privacy, clarity, and a cleaner borrowing experience.
Lenders who understand healthcare cash flow
Medical practices are not the same as other businesses. Reimbursement cycles, payer delays, staffing costs, and practice operations all shape how cash moves. We work with funding partners that understand those realities.
A simple application process
The process is designed to stay straightforward, with a simple 10-minute application and 3 months of business bank statements in many cases.
A real line of credit for growth
The goal is not to bury you in options or push the wrong product. It is to help you access a true line of credit with flexible draws and manageable fixed terms that fit the business.
We can also often help when banks say no, but that is not the main story here. The real value is having a practical funding partner that understands how independent operators use capital to stay steady and keep growing.
A simple process for busy practice owners
Medical practice owners do not need a complicated financing experience.
They need clarity.
A straightforward process typically looks like this:
1. Complete a short application
2. Provide recent business bank statements
3. Review line of credit options with one advisor
4. Choose the structure that best fits the practice
5. Use the line as needed for stability or growth
That kind of process is especially helpful for physicians and practice administrators who do not have time to sort through a confusing menu of products or field calls from multiple brokers.
The bigger picture: cash buffer first, pressure second
The strongest practices do not wait for pressure to make financial planning a priority.
They recognize that healthcare has a built-in delay between service and payment. That delay is not a sign of weakness. It is part of the business model. What matters is whether the practice has enough liquidity to operate confidently through it.
A healthcare business loan or, more specifically, a well-structured medical practice line of credit, can give owners room to:
• Stay current on operations without stress
• Invest in staff and retention
• Upgrade systems and workflows
• Expand on purpose
• Remain independent longer
• Avoid making major decisions under cash pressure
That is why more doctors are building a cash buffer before they need one.
Final thought
If your practice is healthy but your cash flow timing is inconsistent, you are not alone.
The right financing strategy is not about chasing urgency. It is about building stability.
A carefully structured line of credit can help your practice handle reimbursement delays, invest in growth, and keep control where it belongs: with you.
If you want to explore medical practice loans, a healthcare business loan, or a medical practice line of credit built for real-world practice operations, Jonicki Capital Consulting can help you review your options with a clear, simple process.
This article is for general informational purposes only and is not financial, legal, or tax advice. Financing availability, terms, and qualification requirements vary by business and lending partner.