How Restaurants and Retailers Can Bridge the Gap with Smart Credit
Running a successful restaurant, retail store, or service-based business requires a delicate balance of timing, inventory management, and customer demand. However, almost every owner faces an inevitable challenge: the seasonal slowdown. Whether it is the post-holiday retail slump in January and February, the quiet winter months for a neighborhood bistro, or the summer lull for local service contractors, seasonal revenue dips can quietly erode working capital if not managed correctly.
When cash inflow slows down while fixed expenses like rent, insurance, and base payroll remain constant, stress levels rise. Business owners often find themselves scrambling to cover payroll or stock essential inventory for the upcoming bounce-back. Fortunately, you do not have to drain your personal savings or wait weeks for traditional bureaucratic bank approvals to survive the off-season.
At Jonicki Capital Consulting, founded by Rose Kramer, we understand that modern businesses need agile solutions. By utilizing a flexible business line of credit or tailored business loans, operators can bridge cash flow gaps smoothly, keeping their doors open and their teams intact without compromising long-term profitability.
The Reality of Seasonal Cash Flow Squeezes
For restaurateurs, retailers, and service providers, revenue is rarely linear. A thriving boutique or a popular local eatery might generate robust cash flow during peak seasons: such as Q4 holidays or summer tourist rushes: only to see customer foot traffic drop by 20% to 40% during off-peak quarters.
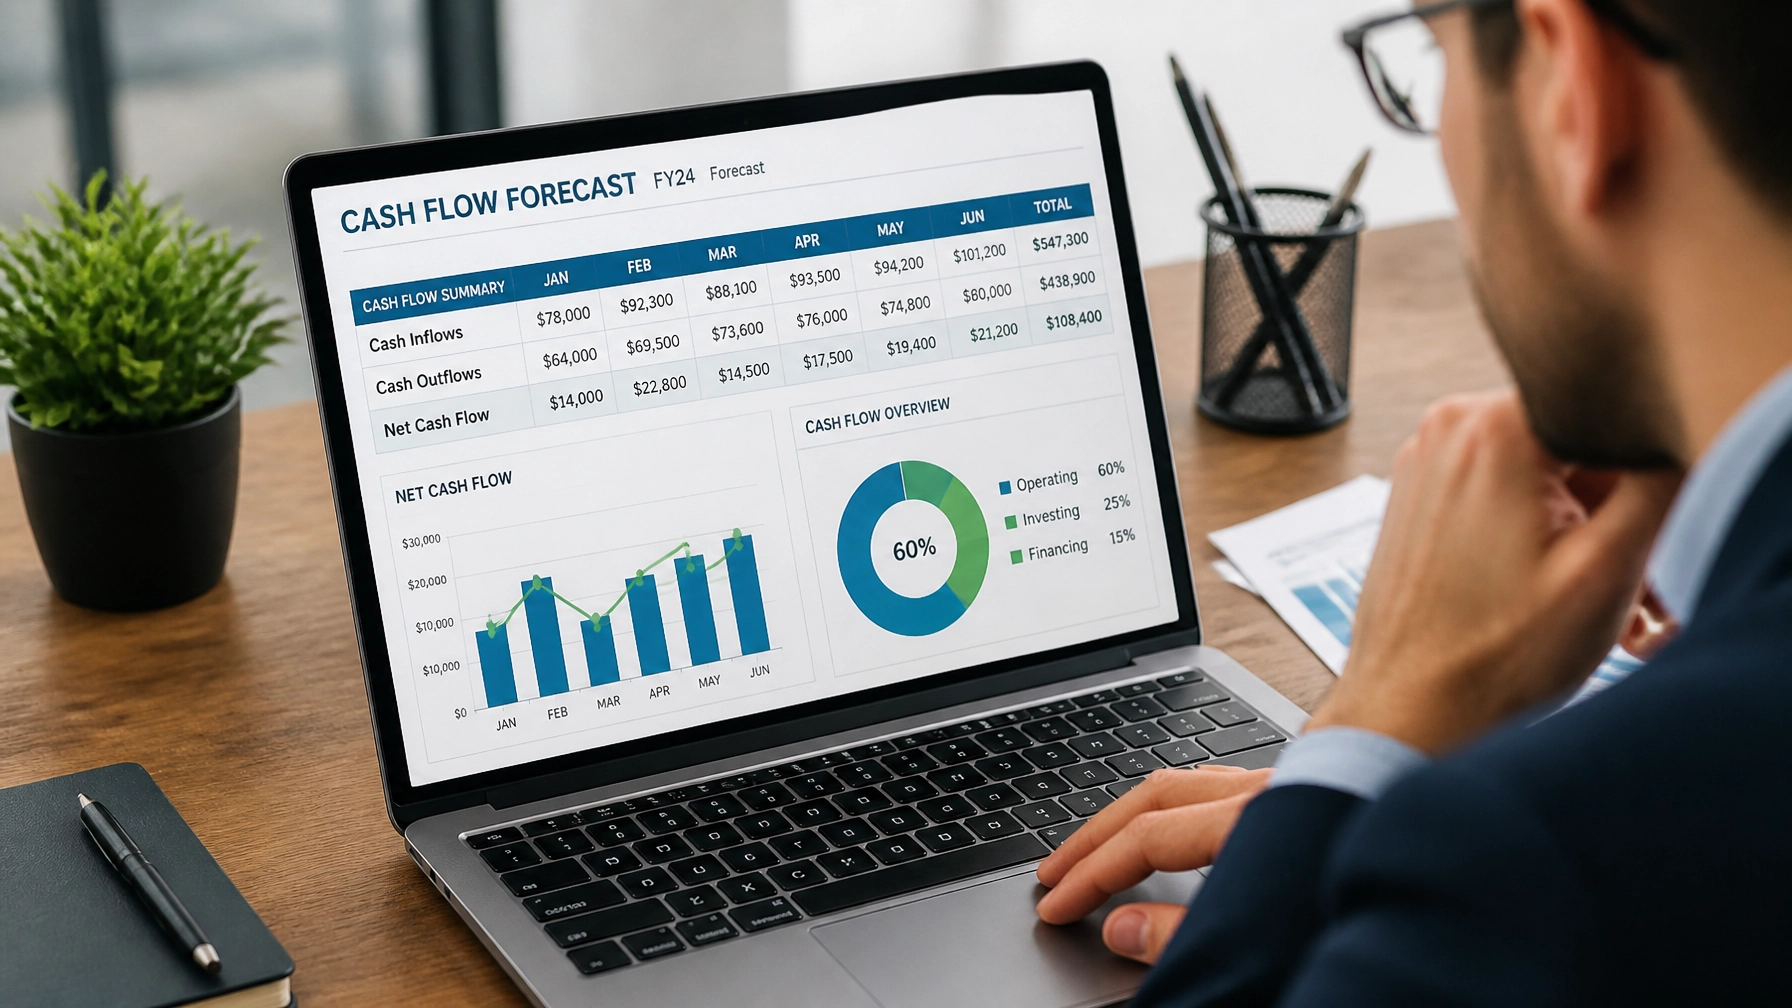
During these slower months, your overhead costs do not take a vacation. Rent is still due on the first of the month, suppliers still expect payment for core inventory, and key staff members must be retained so you are fully staffed when demand returns. When cash reserves are exhausted, business owners need reliable fast business funding to cover short-term operational deficits without disrupting daily workflow.
Why Complex Financing Options Miss the Mark
When seeking capital during a cash crunch, many owners encounter a maze of confusing financial products. It is important to know what to avoid. Traditional SBA loans, while favorable in interest rates, can take months to clear underwriting: making them entirely useless when you need liquidity this week. On the other hand, high-cost merchant cash advances or restrictive factoring agreements often trap businesses in expensive repayment cycles that choke daily margins.
What growing businesses need is straightforward, transparent, and frictionless capital. You do not need complicated equipment loans or restrictive asset encumbrances. You need a financing structure designed around your actual operational performance: one that gives you access to capital when you need it and costs nothing when you don't.
Unlocking Growth with Revolving Business Credit
One of the most effective tools for managing seasonal fluctuations is revolving business credit. Unlike a term loan where you receive a lump sum all at once, a revolving business line of credit functions much like a corporate safety net.
Draw what you need: Only access the funds necessary to cover your slow-season shortfall.
Pay only what you use: Interest accrues exclusively on the drawn balance, not the total credit limit.
Replenish as you earn: As your peak season returns and customer revenue flows back in, your available credit replenishes automatically for future use.
At Jonicki Capital Consulting, our funding solutions are built for speed and simplicity. We emphasize key features designed to keep your business moving forward:
No Collateral Required: Keep your personal and business assets unencumbered. Our unsecured financing options rely on the strength of your existing business performance rather than demanding real estate or heavy machinery as collateral.
Funding Up to $750k: Whether you need a modest $25,000 buffer for winter utility bills or a substantial $500,000 line to prepare for spring inventory expansion, we scale to your potential.
24–48 Hour Approval Times: Time is money. Our streamlined, technology-driven application process delivers fast pre-approvals and funding within 3 to 5 days.
Leverage Existing Revenue: Approval is based on the proven revenue generated from your already-open locations, making it ideal for established operators who have consistent sales history.
How to Secure a Quick Business Line of Credit Online
Waiting in line at a traditional commercial bank or filling out mountains of redundant paperwork is a relic of the past. Today's business owners demand efficiency and transparency.
Securing a quick business line of credit online allows you to navigate the application process directly from your office or restaurant back-office. The process is designed to be streamlined and stress-free:
Step 1: Evaluate Your Cash Gap: Review your historical sales data from the past 24 months to identify the depth and duration of your typical slow season. Calculate your exact monthly shortfall after accounting for baseline revenues.
Step 2: Submit a Simplified Application: Provide basic business details and recent revenue verification through our secure portal at Jonicki Capital Consulting.
Step 3: Review Your Offer: Receive rapid underwriting feedback and clear, transparent terms with no hidden fees or surprise covenants.
Step 4: Access Capital: Funds are deposited directly into your business account, ready to bridge your seasonal gap and protect your cash flow.
If you want to discuss your specific funding requirements with an expert advisor, you can easily schedule a meeting with our team to map out your credit strategy before the slow season deepens.
Best Practices for Maximizing Your Line of Credit
Having access to a robust line of credit is powerful, but pairing it with smart operational habits ensures maximum financial health. To make the most of your business loans and credit lines during slow periods, consider the following strategies:
Plan Ahead: Do not wait until your checking account hits zero before exploring funding options. Securing your line of credit during your busy season: when your financial statements look their strongest: gives you maximum leverage and peace of mind.
Strictly Allocate for Working Capital: Use your credit line exclusively for essential fixed costs (rent, insurance, core payroll) and essential inventory. Avoid using short-term working capital for speculative long-term investments.
Maintain a Repayment Roadmap: Always align your credit draws with your projected seasonal rebound. Know exactly how your upcoming peak revenue will be used to pay down the balance.
Review Operational Efficiency: Combine smart credit utilization with lean staffing schedules, targeted off-peak promotions that protect your profit margins, and weekly cash flow forecasting.
For more insights on optimizing your capital strategy, explore our resource library on the Jonicki Capital Consulting Blog, where we break down the nuances of business financing, growth diagnostics, and credit management.
Turn Seasonal Dips into Strategic Advantages
Seasonal slowdowns are a natural part of operating a restaurant, retail store, or service business, but they do not have to dictate your financial stress or limit your growth potential. By proactively securing a flexible business line of credit, you can protect your cash flow, retain your top talent, and maintain momentum year-round.
At Jonicki Capital Consulting, we specialize in connecting ambitious business owners with reliable, transparent capital solutions tailored to their exact needs. With funding amounts up to $750k, zero collateral requirements, and lightning-fast pre-approvals, we make business financing simple.
Ready to secure your safety net before the next slow season? Apply online today or visit our FAQ page to learn more about how we can support your business growth.