From Paycheck to Profit:
Cash flow problems do not always mean a business is failing.
Many strong businesses run into timing gaps. Payroll is due on Friday. Rent clears on the first. Inventory needs to be reordered now. A new project starts before the client payment hits the account. The business is healthy, but the cash is not arriving at the right time.
That is where a business line of credit can help.
At Jonicki Capital Consulting, founder Rose Kramer and the team help business owners access simple funding that keeps operations moving. For many companies, a line of credit is one of the most practical ways to handle short-term cash flow pressure without overcomplicating the solution.
If you need plain and straightforward information, this is it: a business line of credit gives you access to working capital you can draw from when needed, repay, and use again. It is built for flexibility. It is designed to help keep your cash flow alive.
What Is a Business Line of Credit?
A business line of credit is a revolving credit account for your business.
Instead of receiving one lump sum and making fixed payments on the full amount, you are approved for a credit limit. You draw and pay for only what you need. If you need $20,000, you use $20,000. If you need $80,000 later and your available credit supports it, you can draw again.
That is why many owners prefer revolving business credit for day-to-day cash flow support. It gives them access to capital without forcing them to borrow more than they need at one time.
In simple terms, it works a lot like this:
You get approved for a credit limit
You use only the amount you need
You repay the amount you used
Your available credit opens back up as you pay it down
This structure can make a major difference for businesses that deal with uneven incoming cash, seasonal swings, vendor deadlines, payroll cycles, or growth-related expenses.
Why Cash Flow Gaps Happen Even in Good Businesses
Cash flow gaps are normal.
A business can be profitable on paper and still feel squeezed in real life. That happens because money goes out on one schedule and comes in on another.
Common examples include:
Payroll due before customer payments arrive
Rent, utilities, and overhead hitting at the same time
Inventory needing to be purchased before sales are collected
Marketing expenses paid upfront before results come in
Repairs, supplies, or urgent operating costs that cannot wait
Expansion costs tied to already-open locations producing revenue, but not enough cash on hand today
For owners operating one or more established locations, this is especially common. You may already have revenue coming in from stores, restaurants, offices, service routes, or franchise units. The issue is not whether the business works. The issue is timing.
A business line of credit online can help bridge that timing gap without adding unnecessary complexity.
Why a Simple Line of Credit Makes Sense
When cash flow gets tight, business owners usually want the same thing: a clean, practical option that helps now.
A line of credit can do that because it is:
Flexible: use what you need, when you need it
Reusable: as you repay, credit becomes available again
Fast: Pre-approvals can happen within an hour
Accessible: funding amounts can go up to $750,000
Unsecured: many options require no collateral
That combination matters.
If you are trying to cover payroll, buy inventory, handle a slow receivables cycle, or support operations across existing locations, you do not need a complicated explanation. You need a funding tool that works in the real world.
That is why so many owners search for business funding that is easy to understand and easy to use.
What “No Collateral” Means
One of the first questions owners ask is whether they have to put up property or equipment to get access to capital.
With many business line of credit options, the answer is simple: no collateral required.
That matters for a few reasons:
You may not want to tie up business assets
You may not own real estate to pledge
You may want a cleaner, faster approval process
You may prefer to keep the focus on business performance and revenue
For many borrowers, unsecured access to working capital feels more practical and less stressful. It removes a major barrier and keeps the process straightforward.
How Much Can a Business Line of Credit Provide?
The right amount depends on the business, revenue profile, and overall strength of the file, but many owners are looking for enough room to actually solve the problem.
At Jonicki Capital Consulting, qualified businesses may access a business line of credit with amounts up to $750,000.
That level of credit can support a wide range of real operating needs, including:
Covering payroll during a slow collection cycle
Ordering inventory ahead of a busy season
Managing overhead across multiple open locations
Paying vendors on time to protect supplier relationships
Funding marketing that supports immediate revenue activity
Creating breathing room while existing revenue continues to come in
The key point is not to borrow the maximum just because it is available. The goal is to secure the right amount for your business so you can operate with confidence and stability.
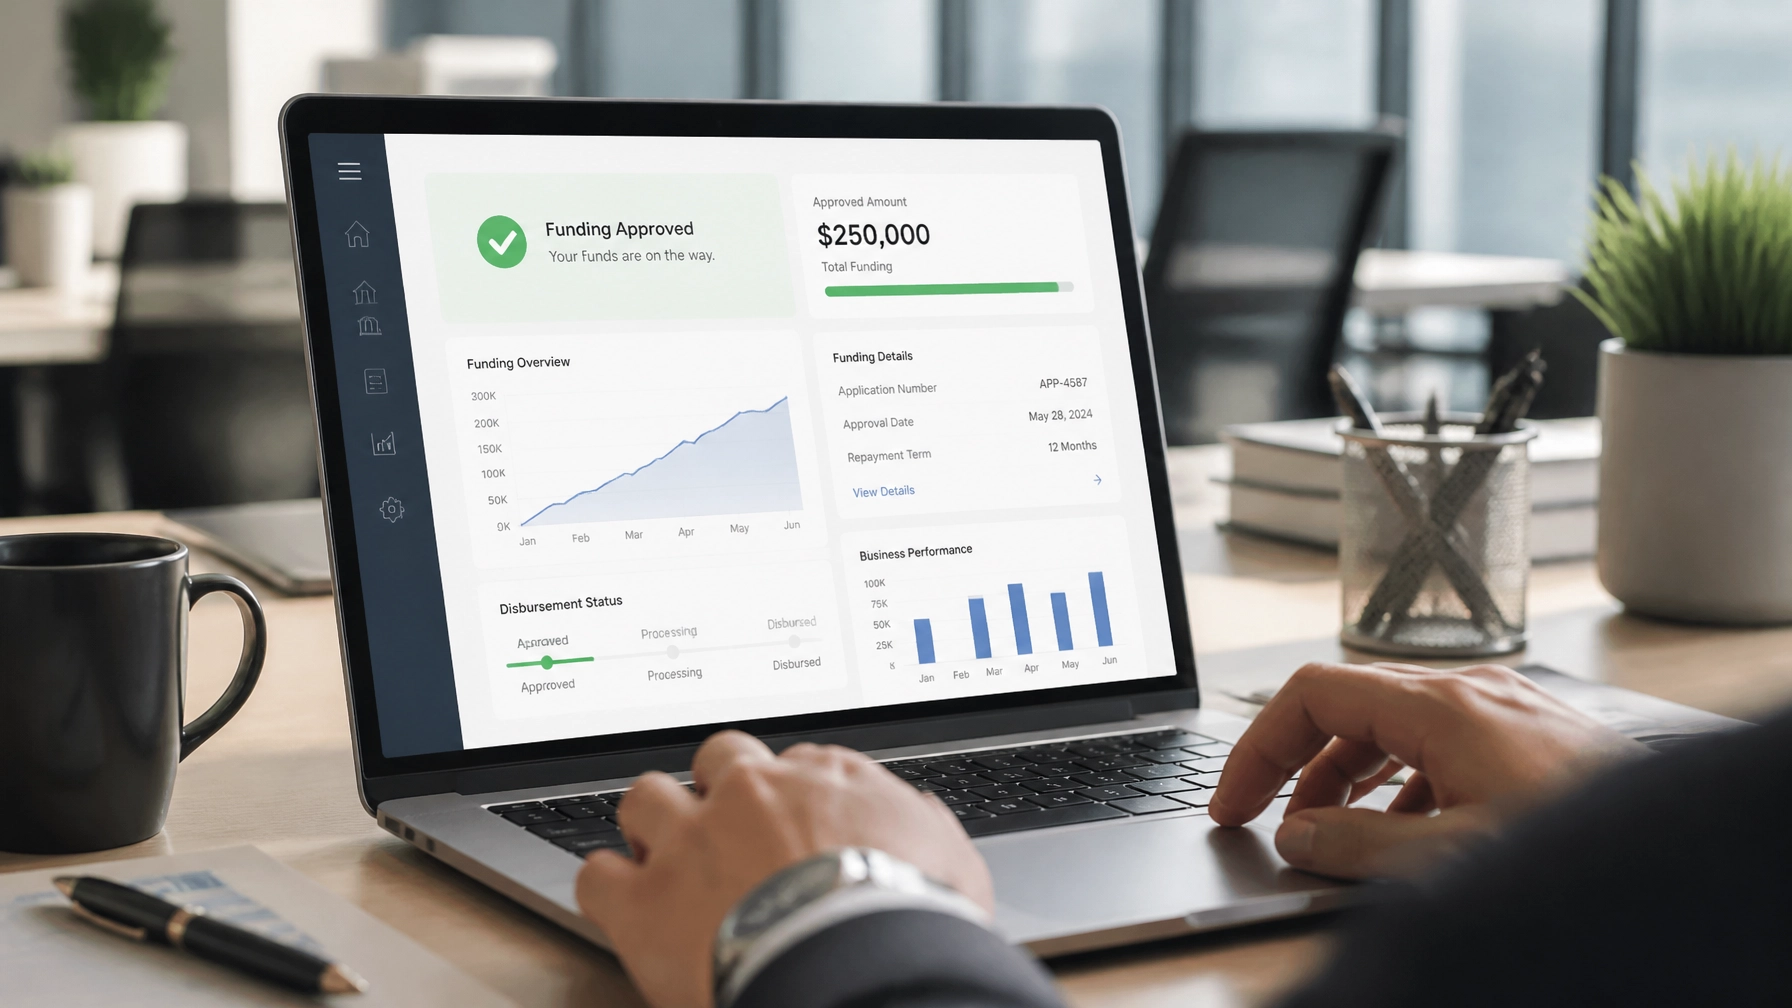
Speed Matters: Approval in 24 to 48 Hours
When a business needs help with cash flow, timing is everything.
Waiting weeks for a decision often does not help. By the time the answer comes back, the payroll issue, inventory need, or vendor deadline has already passed.
That is why speed is one of the biggest reasons owners seek fast business funding.
A quick business line of credit online can often be funded in 3 to 5 days, which is a major advantage for businesses that need to move quickly. Fast access gives owners room to act before a short-term problem becomes a bigger one.
That can mean:
covering payroll on time
securing inventory before a stockout
handling an urgent repair
smoothing out weekly operating expenses
protecting customer experience at already-open locations
The faster the process, the faster the business can get back to normal.
Using Revenue From Already-Open Locations
This is one of the most important points for growing operators.
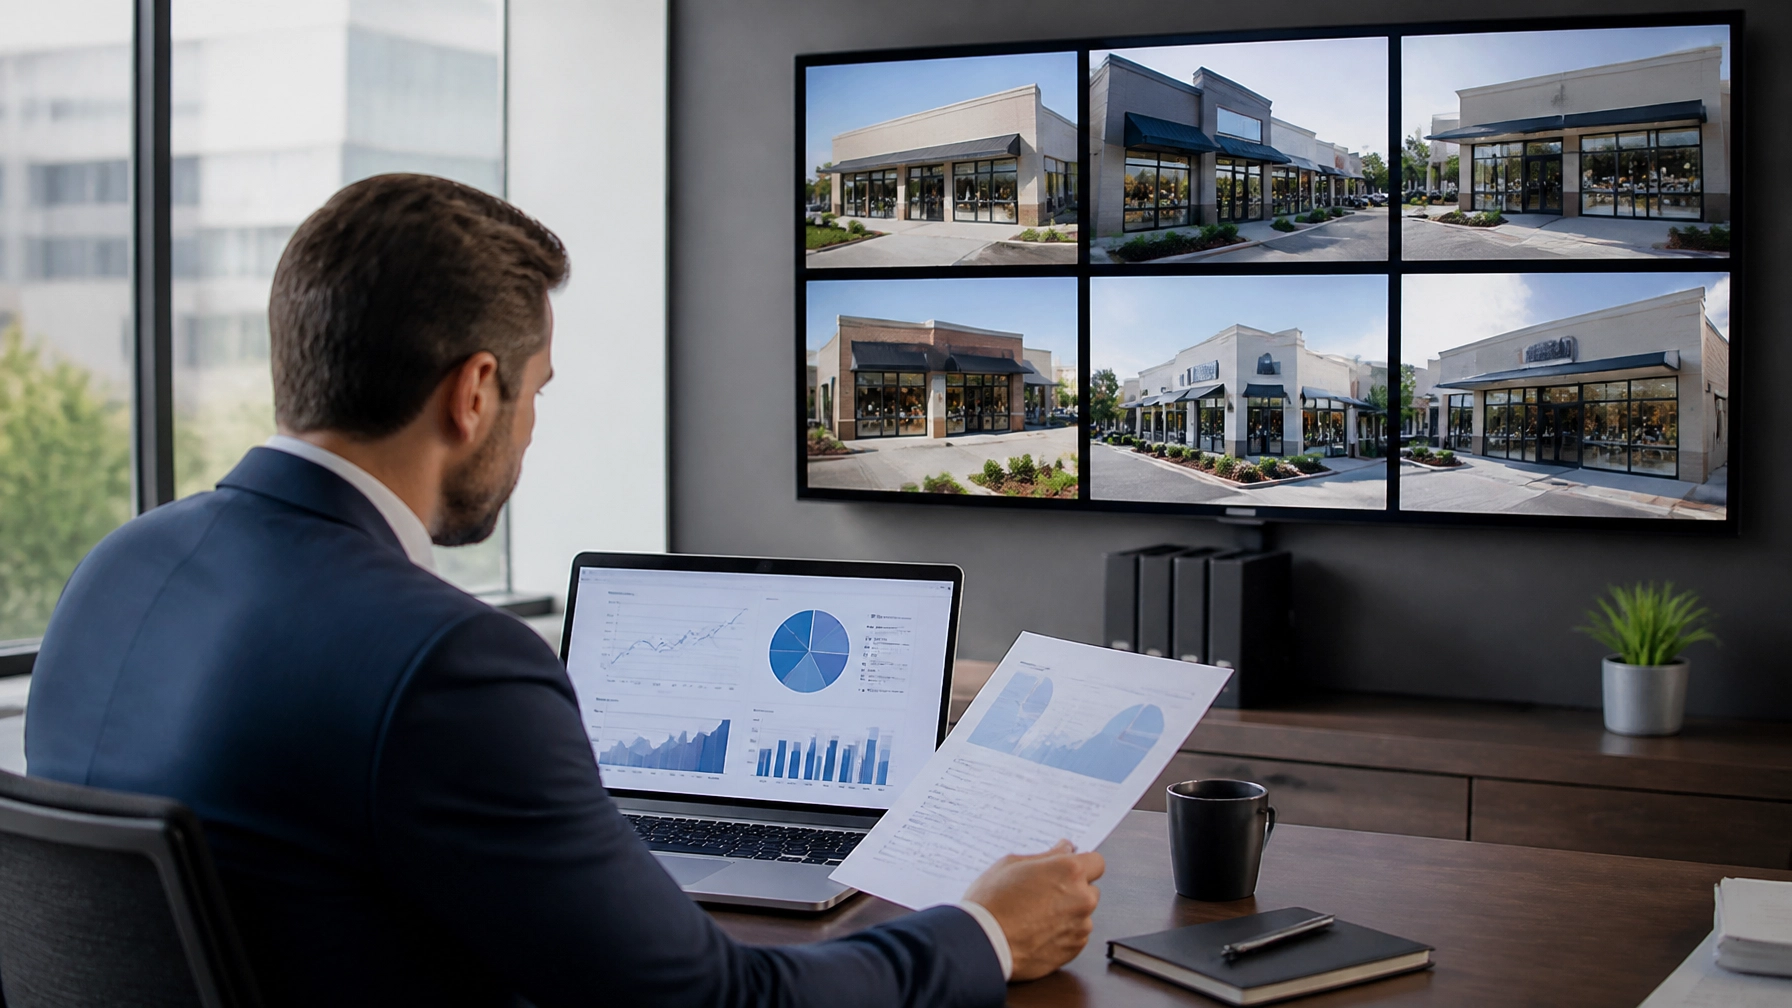
If you already have one or more open locations generating revenue, that existing performance may help support your funding options. In other words, you may be able to leverage the revenue your business is already producing to access capital for cash flow support or operational needs.
That matters for:
franchise owners with operating units
restaurant groups with active locations
retailers with established stores
service businesses with recurring income
multi-location operators managing rolling expenses
Instead of waiting for cash reserves to build slowly, many owners use a business line of credit to make their current revenue work harder. The line gives them room to cover gaps, stabilize operations, and stay focused on growth.
This is not about overcomplicating the capital stack. It is about using the strength of your existing business to access practical working capital.
Common Ways Owners Use Revolving Business Credit
Every business is different, but the use cases are usually simple and familiar.
Owners commonly use revolving business credit for:
Payroll
Payroll does not wait. If receivables are delayed, a line of credit can help keep employees paid on time.
Inventory
Many businesses need to buy inventory before the revenue from those goods is collected. A line can help close that gap.
Rent and Overhead
Fixed expenses keep coming whether customer payments are early or late. Credit can help smooth those cycles.
Vendor Payments
Paying vendors on time can protect relationships and improve purchasing flexibility.
Seasonal Swings
Busy seasons and slow seasons often create uneven cash flow. A line of credit can help level that out.
Growth From Existing Operations
Businesses with already-open locations may use available credit to support day-to-day working needs while revenue continues to cycle in.
Why Simplicity Matters
Most business owners are not looking for a finance lecture.
They want to know:
How much can I qualify for?
How fast can I get approved?
Do I need collateral?
Can this help me cover real operating expenses?
Is the process simple?
Those are the right questions.
A business line of credit is often attractive because the answer to those questions is clear:
funding amounts can go up to $750k
approval can happen in 24 to 48 hours
many options require no collateral
funds can be used to manage normal business cash flow needs
the structure is flexible and reusable
That is exactly why this solution continues to stand out among owners who need straightforward business loans and working capital support.
Final Thought
Cash flow is what keeps a business breathing.
You can have good sales, healthy margins, and strong locations, but if money is tied up at the wrong time, operations can still feel tight. A business line of credit helps solve that problem in a simple, practical way.
With no collateral, access to up to $750,000, and possible 3 to 5 day funding times, this kind of funding gives business owners room to stay current, stay stable, and stay focused.
If your business is generating revenue from already-open locations and you need a straightforward way to manage cash flow gaps, Jonicki Capital Consulting can help you explore the right option.
Learn more at jonicki.com.